Down payment and mortgage insurance in Canada: how much you really need
The minimum down payment in Canada depends on the price, and anything under 20% needs mortgage insurance. Here is how to work out both, with numbers for common price points in Oxford County.
“How much do I need to save?” is usually the first money question buyers ask me. The honest answer is: less than most people think for the down payment, and a bit more than they think once you add insurance and closing costs. Here’s how it works in Canada.
The minimum down payment
The minimum depends on the purchase price, and it’s calculated in layers:
- 5% of the first $500,000
- 10% of the portion between $500,000 and $1,499,999
- 20% of the whole price at $1.5 million or more (mortgage insurance isn’t available at that price)
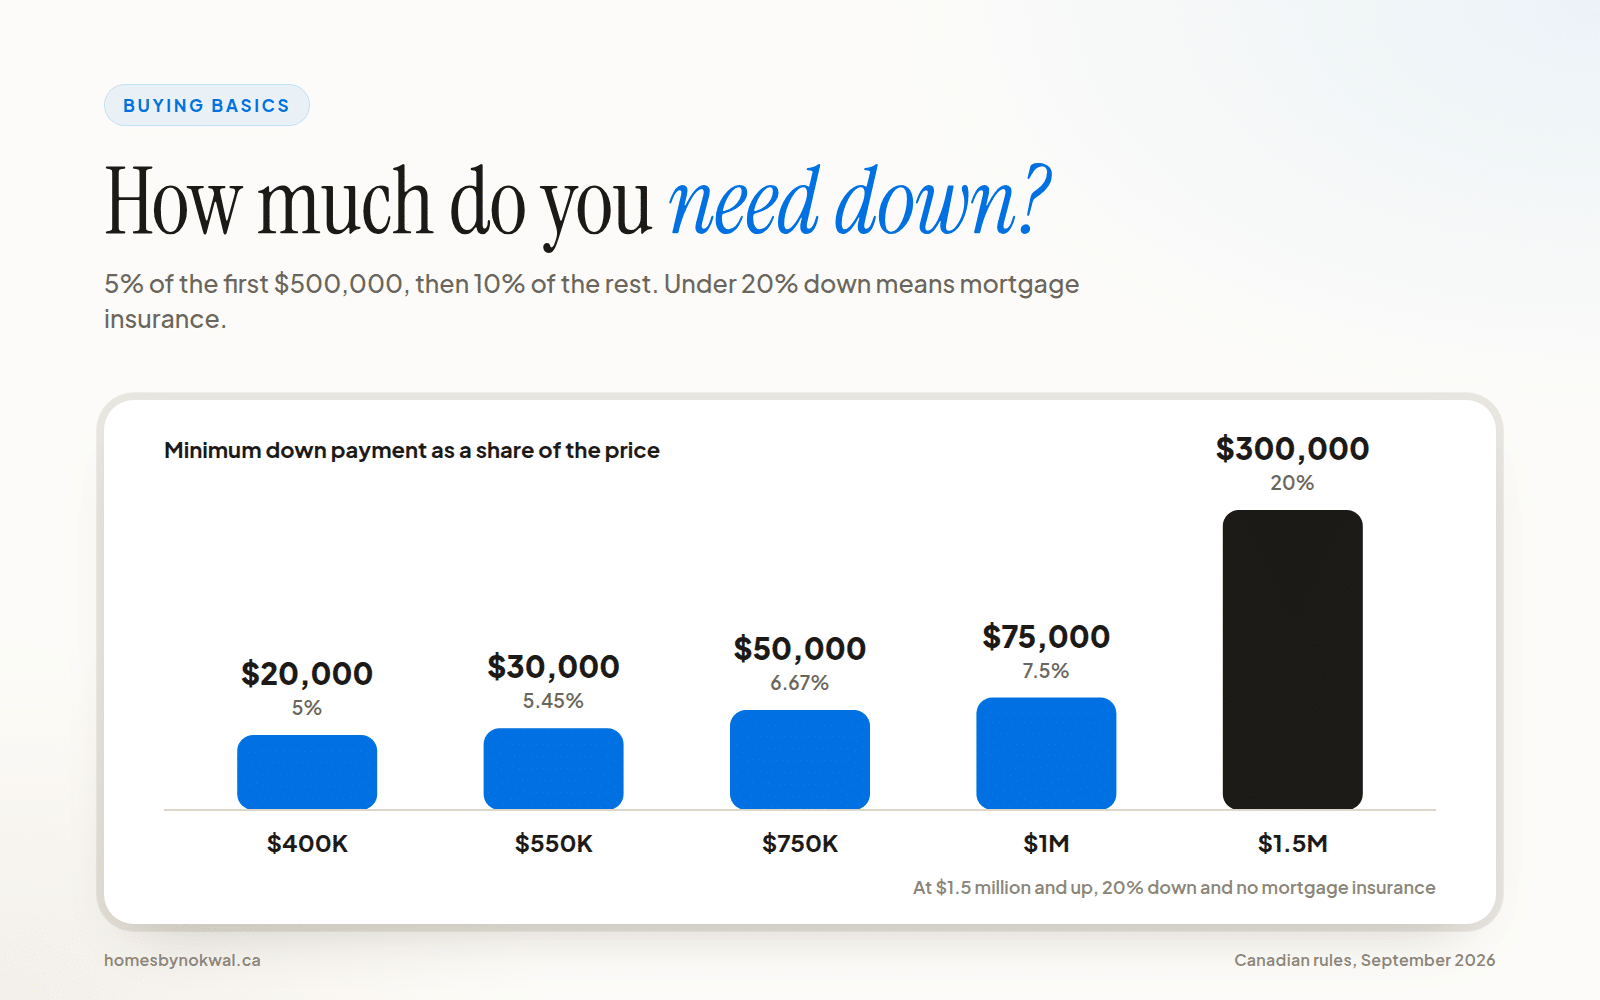
So on a $550,000 home: 5% of $500,000 is $25,000, plus 10% of the remaining $50,000 is $5,000. The minimum is $30,000, about 5.45% of the price.
| Purchase price | Minimum down payment | Share of price |
|---|---|---|
| $400,000 | $20,000 | 5% |
| $550,000 | $30,000 | 5.45% |
| $750,000 | $50,000 | 6.67% |
| $1,000,000 | $75,000 | 7.5% |
| $1,500,000 | $300,000 | 20% |
Mortgage default insurance
If your down payment is under 20%, your mortgage must be insured against default by CMHC, Sagen or Canada Guaranty. The insurance protects the lender, not you, but it’s what makes a 5% down payment possible. It also tends to get you some of the lowest rates available, because the lender’s risk is covered.
The premium is a percentage of the mortgage amount and is normally added to the mortgage:
| Down payment | Premium (share of the loan) |
|---|---|
| 5% to 9.99% | 4.00% |
| 10% to 14.99% | 3.10% |
| 15% to 19.99% | 2.80% |
| 20% or more | No insurance needed |
Choosing a 30-year amortization (available to first-time buyers and buyers of new builds on insured mortgages) adds 0.20% to the premium.
The Ontario catch: Ontario charges 8% sales tax on the premium. It can’t be added to the mortgage, so you pay it in cash at closing.
What that looks like on a $550,000 home
| Down payment | Mortgage | Premium added | Sales tax due at closing |
|---|---|---|---|
| $30,000 (5.45%) | $520,000 | $20,800 | $1,664 |
| $55,000 (10%) | $495,000 | $15,345 | $1,228 |
| $82,500 (15%) | $467,500 | $13,090 | $1,047 |
| $110,000 (20%) | $440,000 | $0 | $0 |
Going from the minimum to 10% down cuts the premium by $5,455 and the mortgage by more than $30,000. Every step up in down payment saves twice: a smaller loan, and a smaller premium on it.
Where the down payment can come from
- Your savings and investments. Lenders want to see where the money came from, usually with 90 days of account history.
- First Home Savings Account (FHSA). Contribute up to $8,000 a year, to a lifetime maximum of $40,000. Contributions are tax-deductible and withdrawals for a first home are tax-free.
- RRSP Home Buyers’ Plan. Withdraw up to $60,000 per person from your RRSP, tax-free, and repay it over 15 years.
- Both together. You can use the FHSA and the Home Buyers’ Plan on the same purchase, up to $100,000 per person.
- A gift from family. Most lenders accept a gift from immediate family with a signed gift letter confirming it doesn’t have to be repaid, and the money in your account before closing.
- Proceeds from selling your current home.
For the full list of programs, including the first-time buyer tax credit and the land transfer tax refund, read first-time homebuyer incentives in Ontario.
Is 20% down always better?
Not always. Putting 20% down means no insurance premium and more flexibility, such as a 30-year amortization at many lenders. But waiting years to save 20% can cost you if prices and rents rise in the meantime, and insured mortgages often come with lower rates.
A good rule of thumb: put down what gets you into the right home with a comfortable payment, and keep an emergency fund. Draining every dollar into the down payment leaves no cushion for a new furnace or a lost paycheque.
Don’t forget closing costs
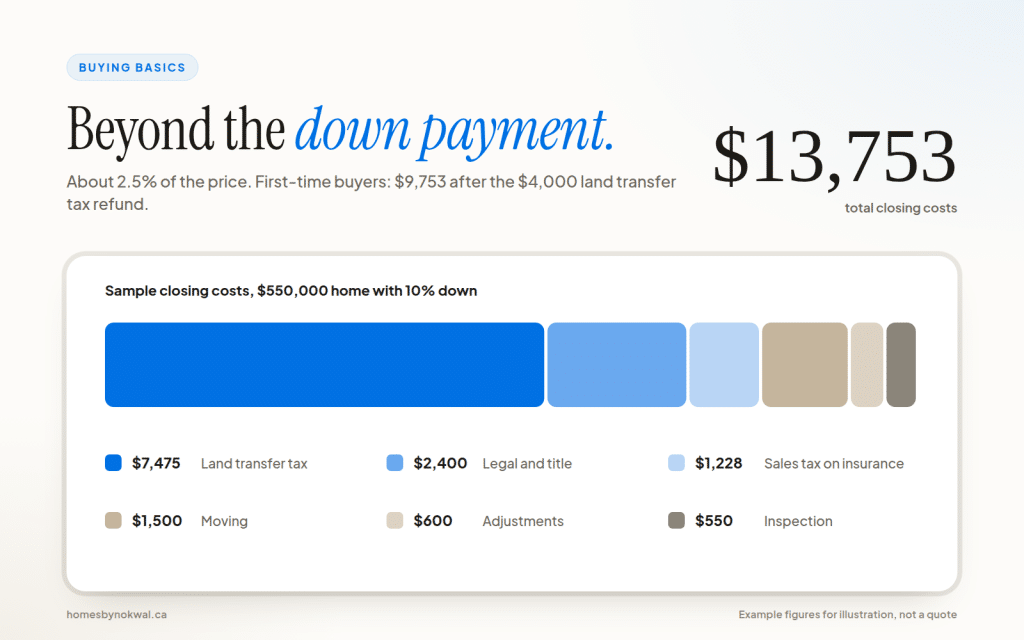
The lender will also want to see that you have money for closing costs, often about 1.5% of the price, on top of the down payment. Land transfer tax, legal fees and the sales tax on your insurance premium all come due on closing day. We break it all down in closing costs in Ontario: what to budget beyond your down payment.
Want to work out your number for a home in Woodstock, Ingersoll, Tillsonburg or anywhere in Oxford County? Reach out and we’ll put a plan together.
Figures are examples for illustration only, based on rules in effect in September 2026. Premiums and program limits can change; confirm current details with your lender, mortgage broker and the Government of Canada.