Ontario home buyer’s guide: 8 steps from budget to keys
The whole Ontario buying process in 8 steps: budget, pre-approval, your team, the search, the offer, conditions, closing costs and closing day, with what each step costs and how long it takes.
Buying a home in Ontario follows the same legal and financial path whether it’s a condo in London, a family home in Woodstock or a farmhouse outside Tavistock. Know the path, and every step feels a lot less stressful.
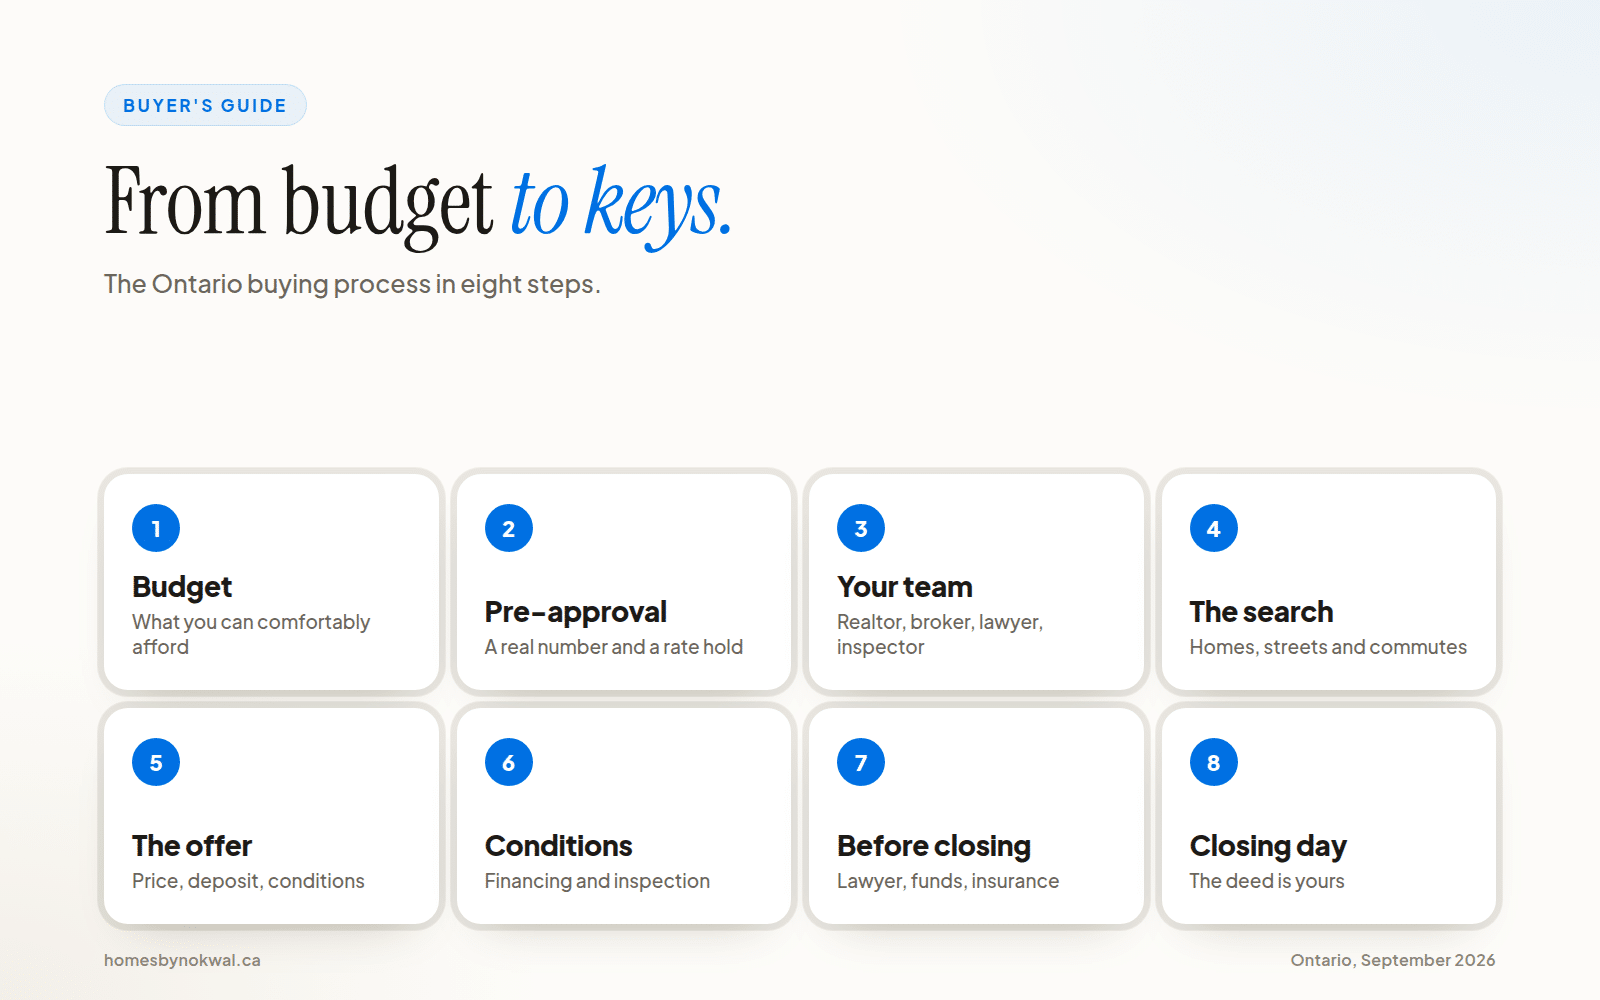
Here’s the whole process in eight steps, with what happens at each one and roughly how long it takes.
| Step | What happens | Typical timing |
|---|---|---|
| 1. Budget | Work out what you can afford | 1 to 2 weeks |
| 2. Pre-approval | A lender confirms your budget and holds a rate | 1 to 5 days |
| 3. Your team | Realtor, mortgage broker, lawyer, inspector | Before you view homes |
| 4. The search | Viewings, neighbourhoods, comparing homes | A few weeks to a few months |
| 5. The offer | Price, deposit, conditions and closing date | 1 to 3 days |
| 6. Conditions | Financing, inspection, insurance | Often 5 business days |
| 7. Before closing | Lawyer, mortgage, funds, insurance | 30 to 90 days, typically |
| 8. Closing day | The deed is registered and you get the keys | 1 day |
Step 1: Know your real budget
Before you look at a single listing, work out what you can comfortably afford, not just what a lender will approve.
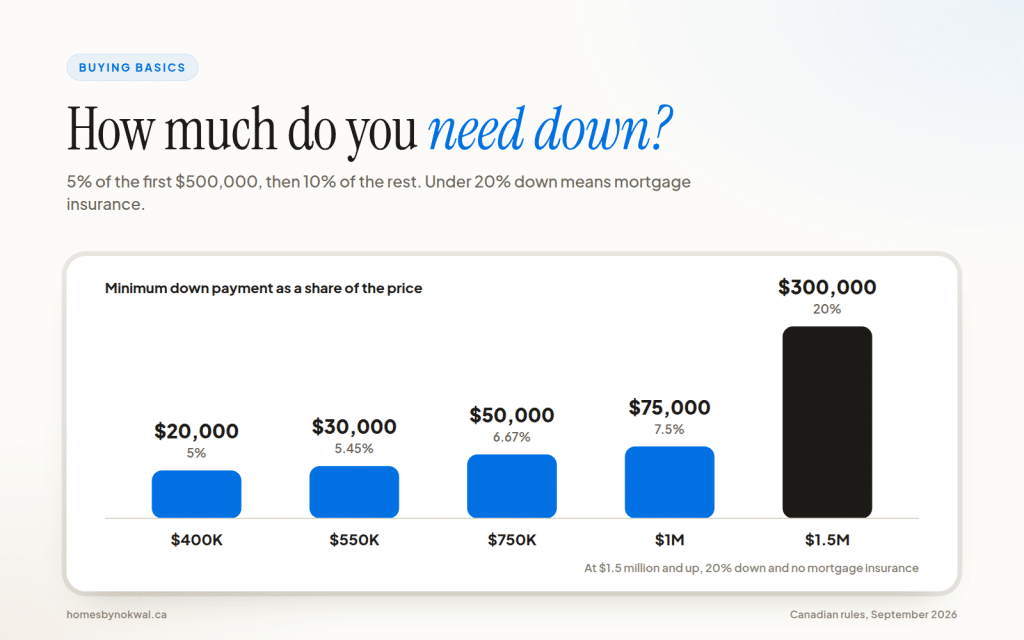
- Down payment: at least 5% of the first $500,000 and 10% of the part above that, up to $1.5 million. At $1.5 million or more you need 20%. See down payment and mortgage insurance in Canada.
- Borrowing limit: lenders use two ratios, GDS and TDS, tested at the stress test rate. See GDS and TDS: the two ratios that decide how much you can borrow.
- Cash for closing: budget roughly 1.5% to 4% of the price on top of your down payment.
- First-time buyer programs: the FHSA, the Home Buyers’ Plan and the land transfer tax refund can add up to tens of thousands of dollars. See first-time homebuyer incentives in Ontario.
Step 2: Get pre-approved
A pre-approval turns your budget into a real number. The lender checks your income, debts and credit, and usually holds an interest rate for 90 to 120 days while you shop. It also shows sellers you’re a serious buyer. A pre-approval isn’t a final approval: the lender will still review the specific home you buy.
Step 3: Build your team
- Realtor: finds and compares homes, checks what similar homes sold for, writes and negotiates your offer. Under Ontario’s Trust in Real Estate Services Act (in force since December 2023), your agreement with your brokerage must be in writing, and you’ll receive RECO’s information guide explaining your options.
- Mortgage broker or lender: finds the right mortgage and handles the approval.
- Real estate lawyer: required to close in Ontario. Searches the title, registers the purchase and handles the money.
- Home inspector: checks the roof, structure, electrical, plumbing and heating before you commit.
Step 4: Search with a plan
Write down your must-haves and your nice-to-haves before you start viewing, then stick to them. In Woodstock and Oxford County, the big questions are usually:
- Freehold or condo? With freehold you own the land. With a condo you share common areas and pay monthly fees, which lenders count in your ratios.
- City or village? Woodstock, Ingersoll and Tillsonburg have city services; rural homes may have a well and septic system that need their own inspections.
- Commute: check the drive at the time of day you’ll actually make it.
Browse homes for sale or compare areas on the Communities page, and save the searches you like so new listings come to you.
Step 5: Make an offer
When you find the right home, we write an Agreement of Purchase and Sale. The key parts:
- Price: based on what comparable homes have sold for, not just the asking price.
- Deposit: often 1% to 5% of the price, usually delivered within 24 hours of acceptance and held in trust. It counts toward your down payment.
- Conditions: your safety nets, such as financing and home inspection.
- Closing date: when ownership changes hands and you get the keys.
If there are competing offers, the seller’s agent must tell every buyer how many offers there are. Sellers can also choose to share the terms of competing offers with every bidder, without identifying who made them.
Step 6: Firm up the deal
During the conditional period, your lender does its final approval (often including an appraisal), your inspector checks the home, and you arrange home insurance. Once everything checks out, you sign a waiver and the deal is firm. If a condition isn’t met, you can usually walk away with your deposit.
Step 7: Get ready for closing
Your lawyer searches the title, reviews the survey or title insurance, prepares the documents and tells you exactly how much money to bring. A few days before closing, you’ll sign at the lawyer’s office (or online) and send the balance of your funds.
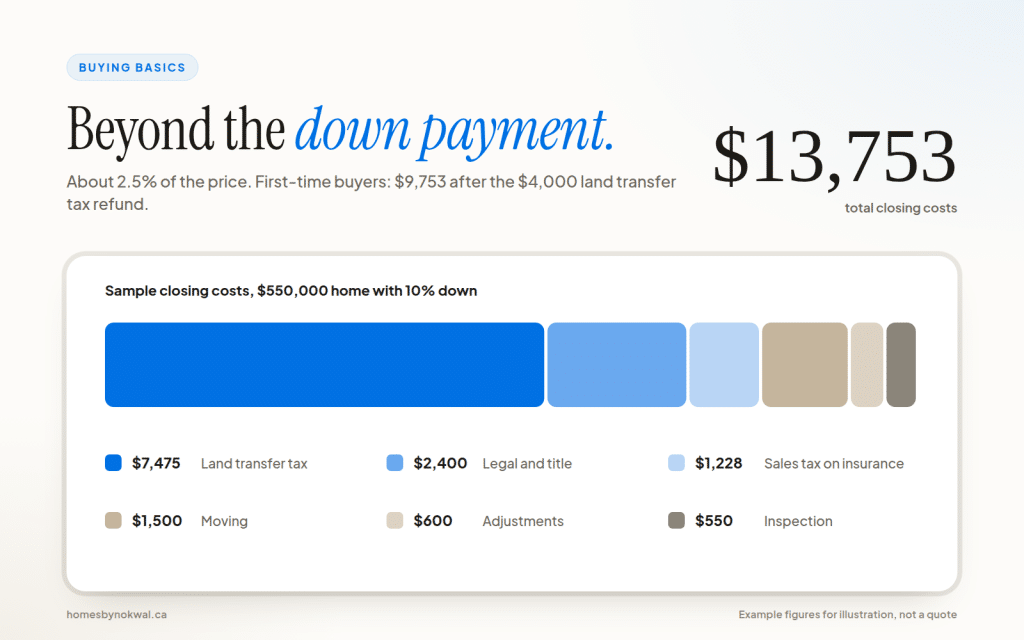
Closing costs usually include land transfer tax, legal fees, title insurance, the 8% sales tax on any mortgage insurance premium, and adjustments for property taxes and utilities. See closing costs in Ontario for a sample budget.
Step 8: Closing day
Your lawyer and the seller’s lawyer exchange funds and documents, and the deed is registered in your name. Once registration is confirmed, you pick up your keys. Then it’s time to set up utilities, update your address and enjoy your new home.
Ready when you are
Whether you’re buying your first home or your fifth, I’ll walk you through each step and make sure nothing is missed. New to mortgages? Start with how a mortgage works in Ontario, or download the free home buying basics guide in English, Hindi or Punjabi.
General information for buyers in Ontario as of September 2026, not legal or financial advice. Timelines vary with every purchase; your lawyer, lender and realtor will guide you through yours.