First-time homebuyer incentives in Ontario: the 2026 guide
The FHSA, the $60,000 Home Buyers' Plan, the land transfer tax refund, the tax credit and the new-home HST rebates: every first-time buyer program in Ontario, with the 2026 limits and what you could claim on a Woodstock home.
Buying your first home is a big step, and the government programs that help with it change more often than most people realize. Several limits went up in the last two years, one program ended, and new rebates for newly built homes arrived in 2025 and 2026.
This guide covers every program a first-time buyer in Ontario should know about in 2026, who qualifies, and what they could be worth on a real purchase.
The programs at a glance
| Program | What you get | Who it’s for |
|---|---|---|
| First Home Savings Account (FHSA) | Save up to $40,000 tax-free ($8,000 a year) | First-time buyers (4-year rule) |
| RRSP Home Buyers’ Plan | Withdraw up to $60,000 from your RRSP tax-free | First-time buyers (4-year rule) |
| First-time Home Buyers’ Tax Credit | $10,000 credit, worth up to $1,500 | First-time buyers (4-year rule) |
| Ontario land transfer tax refund | Up to $4,000 | Never owned a home anywhere |
| Toronto land transfer tax rebate | Up to $4,475 | Toronto purchases only |
| New-home GST and HST rebates | Up to $50,000 federal, and more in Ontario for 2026 | Buyers of newly built homes |
| 30-year insured amortization | Lower monthly payments | First-time buyers and new builds |
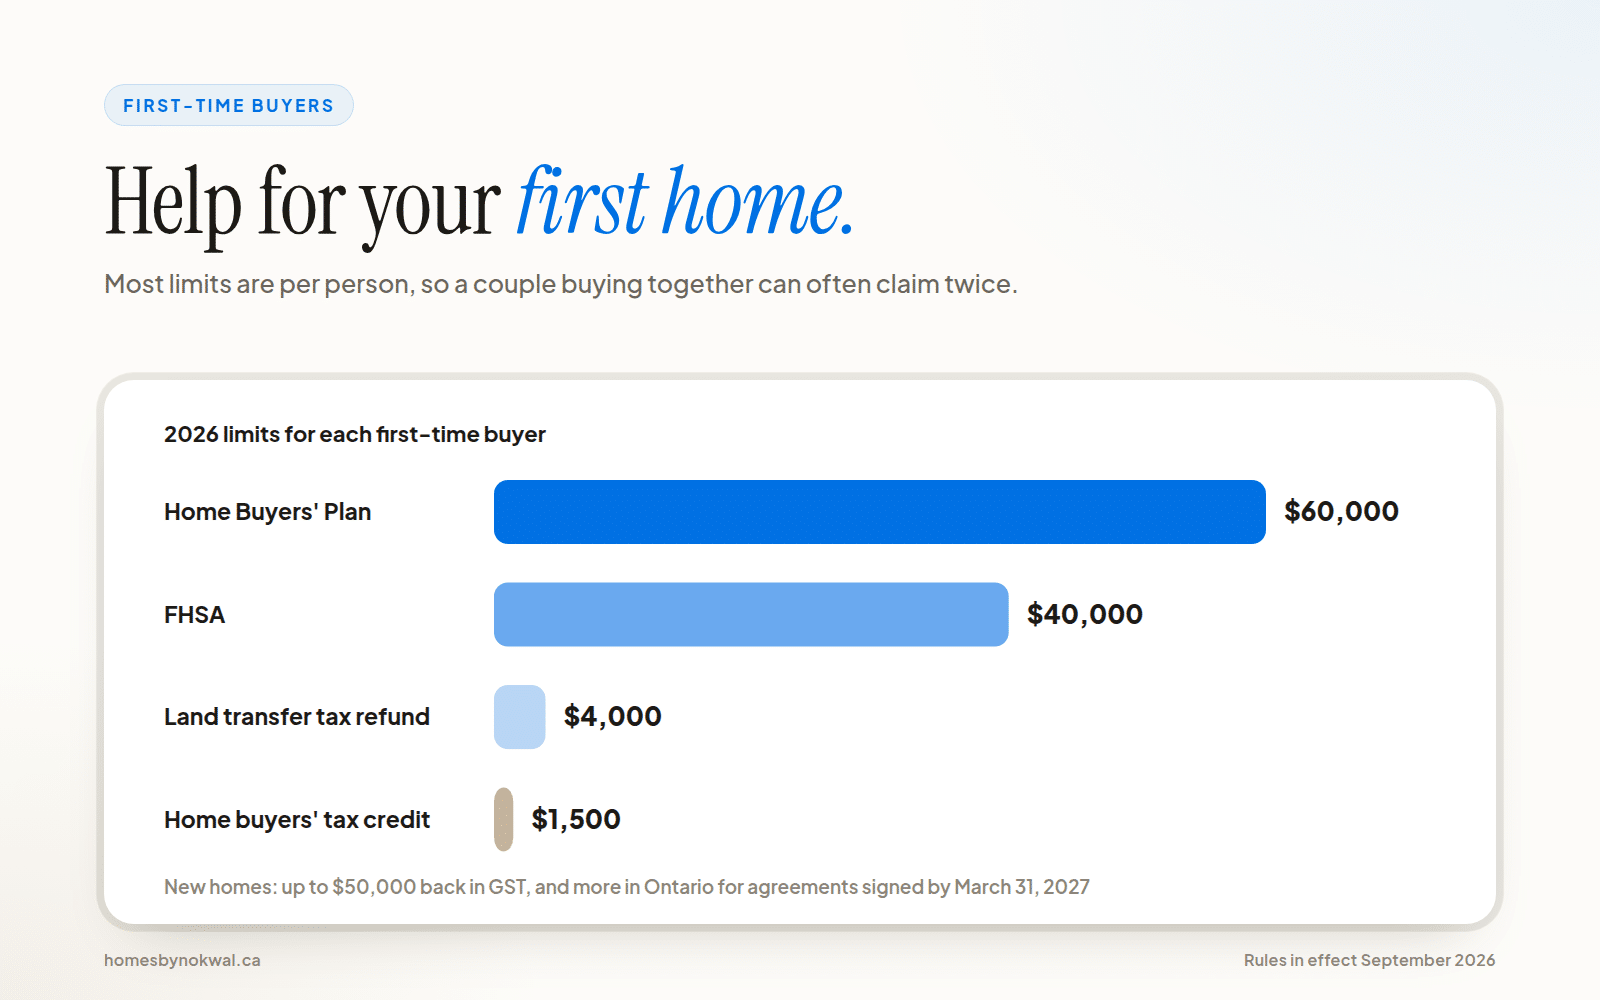
Most amounts are per person, so a couple buying together can often claim twice.
Who counts as a first-time buyer?
There are two different definitions, and it matters which one applies:
- Federal programs (FHSA, Home Buyers’ Plan, tax credit): you generally qualify if you didn’t live in a home that you, or your spouse or common-law partner, owned in the current year or the previous four calendar years. So someone who sold a home five or more years ago can qualify again.
- Ontario land transfer tax refund: you must never have owned a home, or an interest in a home, anywhere in the world. Your spouse also can’t have owned a home while they were your spouse.
1. First Home Savings Account (FHSA)
The FHSA combines the best of an RRSP and a TFSA. Contributions are tax-deductible, investments grow tax-free, and withdrawals for your first home are tax-free.
- Contribute up to $8,000 a year, to a lifetime maximum of $40,000.
- Unused room carries forward, up to $8,000, so you can put in as much as $16,000 in one year if you skipped the year before.
- The account can stay open for up to 15 years, or until the end of the year you turn 71.
- If you don’t buy, you can move the money into your RRSP without using RRSP room.
Opening an FHSA early starts the room building, even if you only put in a small amount at first.
2. RRSP Home Buyers’ Plan (HBP)
The Home Buyers’ Plan lets you withdraw money from your RRSP for your down payment, tax-free.
- The limit is $60,000 per person (it was $35,000 until April 2024), so $120,000 for a couple.
- You repay it to your RRSP over 15 years, normally starting in the second year after the withdrawal. A missed repayment is added to your taxable income for that year.
- Money must be in your RRSP for at least 90 days before you withdraw it under the plan, or you lose the tax deduction on that contribution.
You can use the FHSA and the Home Buyers’ Plan on the same purchase, up to $100,000 per person.
3. First-time Home Buyers’ Tax Credit
When you buy your first home, you can claim a $10,000 non-refundable federal tax credit on your return for that year. At the 15% federal rate it’s worth up to $1,500. Couples can split it, but the total is still $1,500.
4. Ontario land transfer tax refund
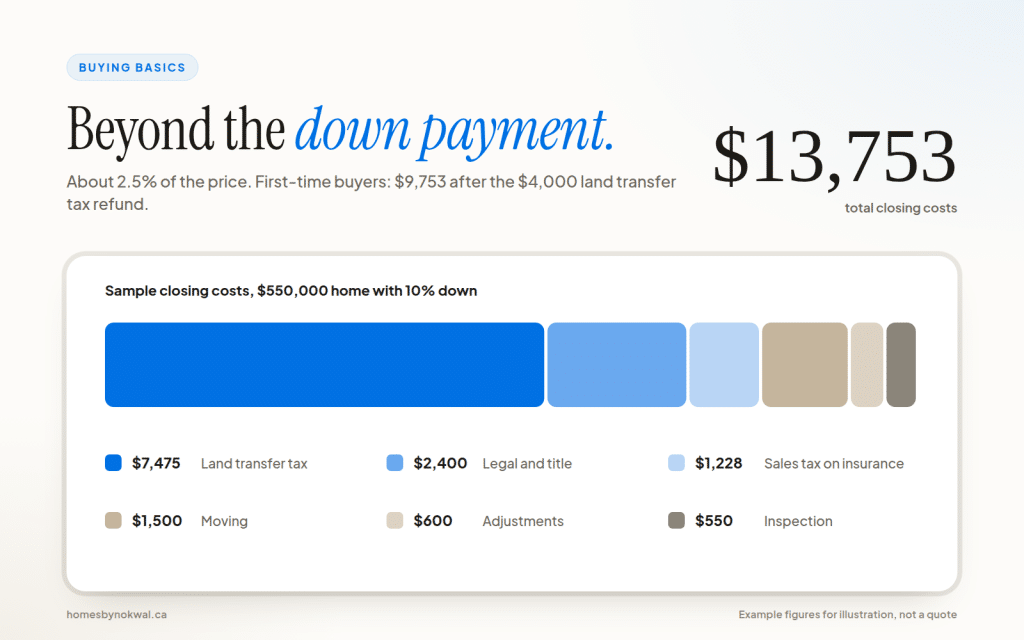
Ontario charges land transfer tax on every purchase, and it’s usually the biggest closing cost. First-time buyers can get up to $4,000 of it back, which covers the whole tax on homes up to about $368,000.
| Purchase price | Land transfer tax | First-time buyer pays |
|---|---|---|
| $400,000 | $4,475 | $475 |
| $550,000 | $7,475 | $3,475 |
| $750,000 | $11,475 | $7,475 |
To qualify you must be at least 18, a Canadian citizen or permanent resident, move in within 9 months, and meet the “never owned” rule above. Your lawyer normally claims the refund when the deed is registered, so it comes straight off your closing bill. Buying in Toronto adds a municipal land transfer tax with its own first-time rebate of up to $4,475; Woodstock and Oxford County have no municipal tax.
5. Rebates on newly built homes
Resale homes don’t carry HST, but new homes from a builder do, and 2025 and 2026 brought major new relief:
- Federal First-Time Home Buyers’ GST rebate: first-time buyers of a new home can recover the full 5% GST on homes up to $1 million, worth up to $50,000, phasing out between $1 million and $1.5 million. It became law in March 2026 and covers agreements with a builder signed from spring 2025 until the end of 2030.
- Ontario’s enhanced HST rebate: for agreements with a builder signed between April 1, 2026 and March 31, 2027, eligible buyers (not only first-time buyers) of a new home up to $1 million can have the full 13% HST rebated, up to $130,000, with partial relief up to $1.85 million. The home must be a primary residence or a residential rental, and construction deadlines apply.
- Ontario’s regular new housing rebate: outside those rules, the long-standing provincial rebate of up to $24,000 still applies.
These rules are detailed and still being rolled out; the CRA expects to start processing the Ontario enhanced rebate in fall 2026. Before you sign with a builder, have your lawyer confirm exactly which rebate applies and whether the builder credits it on closing or you apply yourself.
6. 30-year amortization for first-time buyers
Since December 2024, first-time buyers (and anyone buying a newly built home) can take a 30-year amortization on an insured mortgage, meaning less than 20% down. The monthly payment is lower, but the insurance premium goes up by 0.20% and you pay more interest over time. Insured mortgages are also now available on homes up to $1.5 million. See how a mortgage works in Ontario for the numbers.
A program that has ended
The First-Time Home Buyer Incentive, the federal shared-equity mortgage, closed to new applications in March 2024. If you see it mentioned, it’s out of date.
What a first-time couple could claim
Two first-time buyers purchasing a $550,000 resale home in Woodstock, each with a full FHSA:
| Benefit | Example value |
|---|---|
| FHSA withdrawals, tax-free (2 × $40,000) | $80,000 toward the down payment |
| Tax refunds on FHSA contributions (depends on income) | roughly $16,000 to $27,000 combined |
| Ontario land transfer tax refund | $4,000 |
| First-time Home Buyers’ Tax Credit | $1,500 |
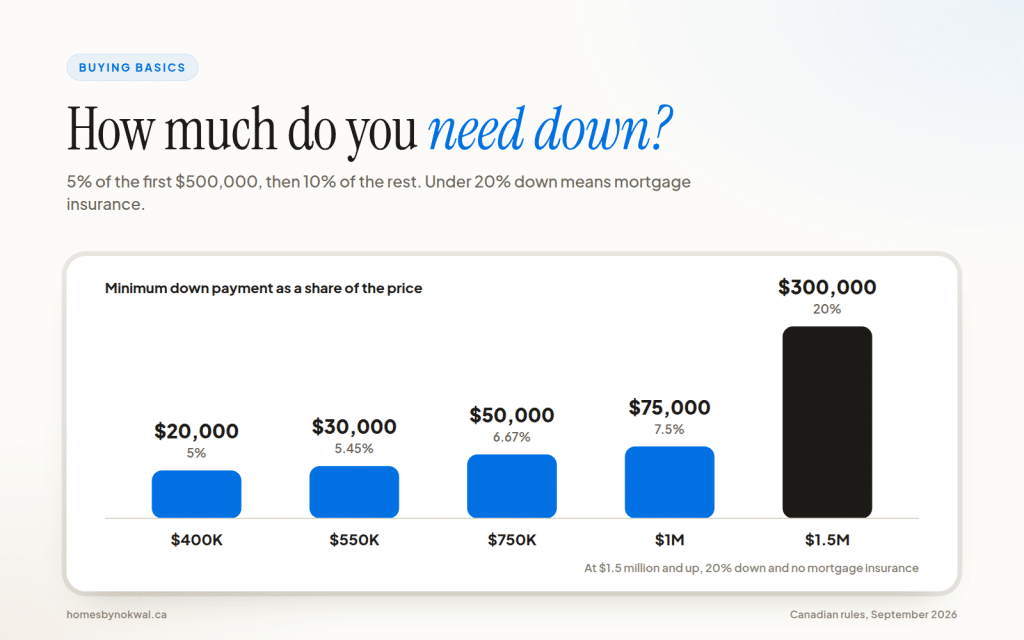
With $80,000 down (about 14.5%), their mortgage insurance premium drops to 3.10% of the loan, and they could still add up to $60,000 each through the Home Buyers’ Plan if they wanted to reach 20% and skip insurance entirely.
Put the programs to work
The right mix depends on your income, your savings and when you plan to buy. A good first step is opening an FHSA now, then talking to a mortgage professional about how much you can borrow. For the full buying process, read the Ontario home buyer’s guide, and for the money side, down payment and mortgage insurance in Canada and closing costs in Ontario.
If you’re buying your first home in Woodstock or anywhere in Oxford County, I’ll help you plan it step by step.
General information based on rules in effect in September 2026, not tax, legal or financial advice. Program rules and limits change; confirm your eligibility with the CRA, the Government of Ontario, your lawyer and your financial advisor.